TECH Signal 167
Report: AI glasses shipments surged 263% in H1 2026 as Apple prepares to enter the market
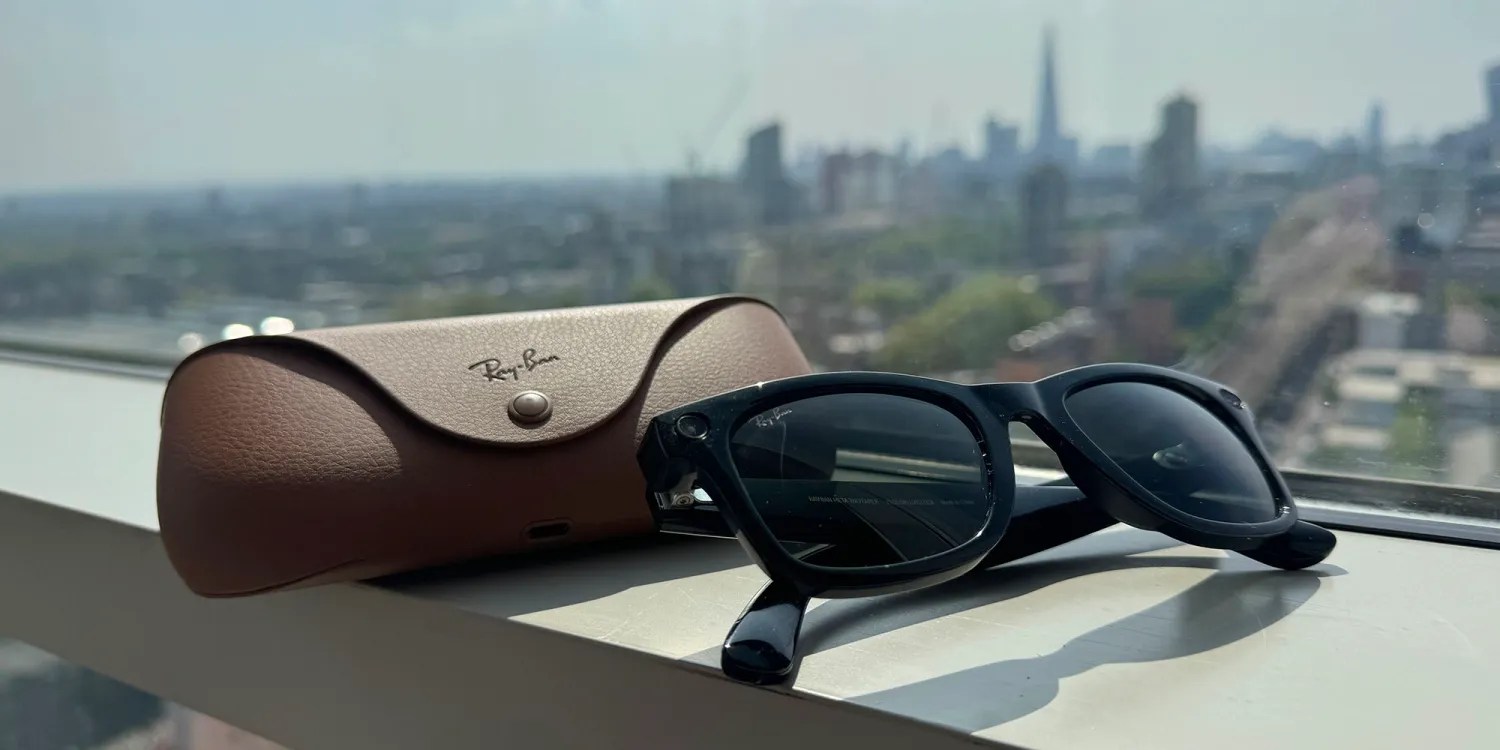 ↗
Counterpoint Research reports that global AI glasses shipments increased by 263% in the first half of 2026, with Meta holding a 94% share of the display-less segment.
The rapid growth signals a shift from niche experimentation to mass-market adoption, driven primarily by Meta's dominance in the display-less category. For engineers, this validates the hardware form factor and suggests that agentic AI and low-power sensing technologies will become standard requirements for wearable interfaces. The looming entry of Apple in 2027 is expected to intensify competition and accelerate the development of privacy-focused alternatives to camera-equipped devices.
Written by elseif from the cluster below · every claim links back to a sourceThe three things worth knowing
Meta accounted for 94% of global display-less AI glasses shipments in H1 2026, with volumes growing 260% year over year.
The AR and AI glasses segment, which includes optical see-through displays, saw shipments surge 449% year over year, led by Rokid and Meta.
Apple is reportedly targeting a 2027 launch for its own display-less smart glasses, relying on Siri and Apple Intelligence, while facing growing privacy scrutiny of camera-equipped competitors.
THE READ
What the cluster adds up to.
Counterpoint Research data indicates a significant acceleration in the AI glasses market, with global shipments for the display-less segment surging 263% in the first half of 2026. This growth is heavily concentrated, as Meta captured 94% of the market share in this specific category, while Xiaomi and Alibaba each held 1%. The dominance of Meta's second-generation devices, which have sold over 7 million units in 2025, suggests that the initial lack of traction for first-generation hardware has been overcome by improved product-market fit.
The market is bifurcating into two distinct technical categories: display-less audio-focused glasses and AR glasses with optical see-through displays. While the display-less segment grew 263%, the AR and AI segment experienced a more dramatic 449% year-over-year increase, though from a smaller base. In the AR segment, Rokid leads with 41% share, followed by Meta at 37%, indicating that the hardware complexity of integrating displays and optical components is creating a different competitive landscape than the simpler audio-only form factor.
Adopting this technology stack involves significant trade-offs regarding privacy and user acceptance. Meta's camera-equipped glasses have faced increasing scrutiny and the "perv glasses" label due to reports of non-consensual filming, which poses a reputational and regulatory risk for the entire category. Counterpoint anticipates that this pressure will drive the development of new form factors, such as camera-free audio glasses or devices where cameras are used solely for contextual understanding rather than media capture, requiring engineers to design for privacy by default.
The entry of Apple, reportedly targeted for 2027, is expected to disrupt the current market equilibrium. Apple's devices are expected to rely heavily on Siri and Apple Intelligence, with cameras, microphones, and speakers integrated into the frame, while a more advanced AR version remains several years away. This timeline suggests that the near-term market will remain dominated by display-less devices, but the long-term trajectory points toward agentic AI glasses that offer proactive, context-aware experiences powered by ultra-low-power sensing and computing technologies.
For component vendors and software developers, the next phase of growth is tied to the maturation of agent-integrated software and operating systems. The market is moving beyond simple voice assistants toward systems that can interpret context and act autonomously, which demands advancements in voice interaction and low-power computing. Engineers building for this space must account for the dual requirement of high-performance AI processing and the strict power constraints inherent in wearable form factors, as well as the emerging regulatory landscape surrounding biometric and visual data collection.
Written by elseif from the cluster below · checked for specifics the sources never containedTHE CLUSTER